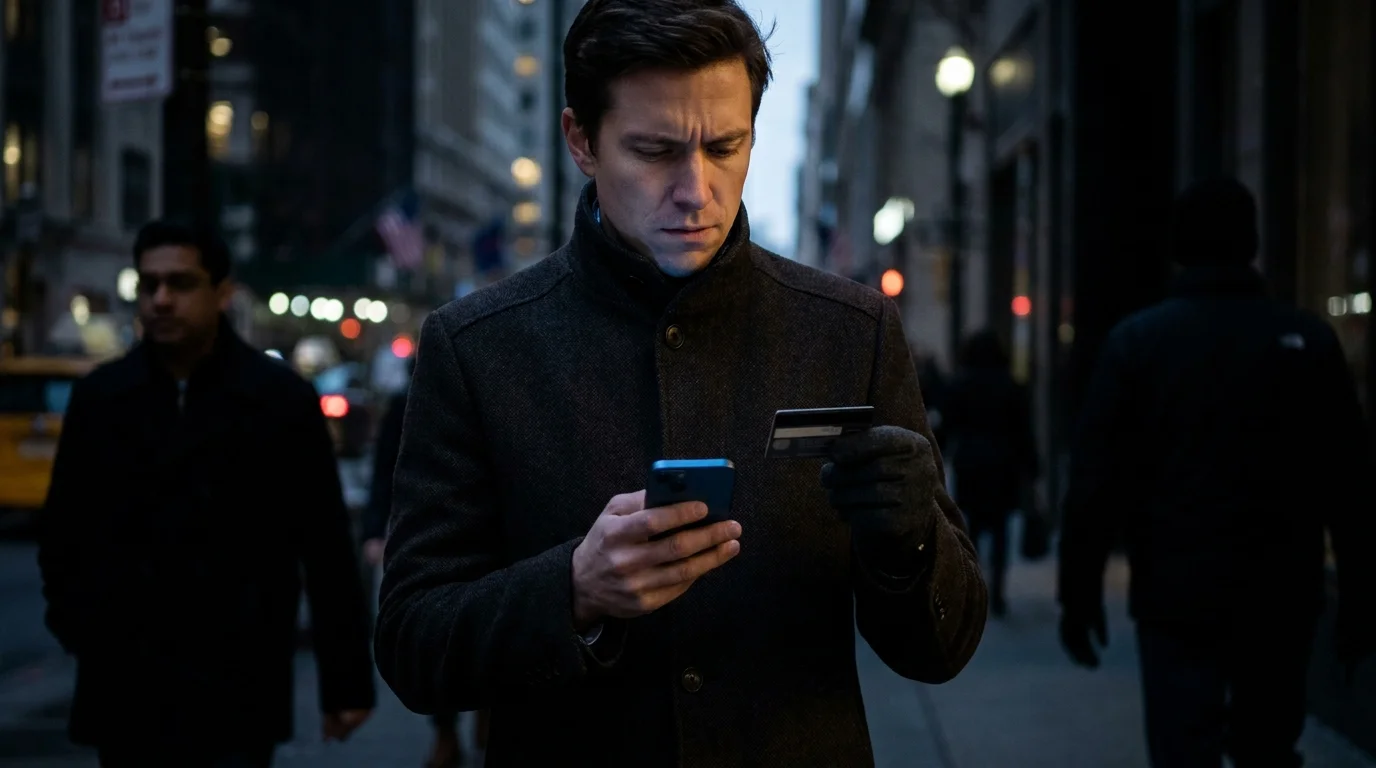
The kitchen is quiet, save for the gentle hum of the refrigerator and the tap-water settling in your glass. Your phone buzzes against the countertop, its illuminated screen displaying the familiar local area code and the exact name of the regional bank branch you pass on your morning drive. You pick it up without thinking twice, greeted not by a disjointed international delay, but by an urgent, crisp voice delivering gut-wrenching news: your checking account has been frozen following an unauthorized two-thousand-dollar transfer attempt.
Your chest tightens instantly. The caller sounds polished, calm, and reassuring, offering to walk you through a quick security reset to salvage your funds before the transaction settles. They ask you to verify a six-digit code arriving via text message right as you speak. Every natural human instinct tells you to cooperate, to extinguish the fire before your rent or mortgage payment bounces. Yet, in that exact sliver of adrenaline-soaked silence, you are standing on the edge of a carefully constructed digital stage set.
The person on the other end does not work for your bank. They are not sitting under fluorescent branch lighting reviewing a ledger; they are sitting behind a VoIP terminal running a script. By weaponizing the precise caller identity of your neighborhood credit union, they have turned your own cautious vigilance into the crowbar that pries your financial identity wide open.
The Mirage on Your Screen: Why Caller ID Is Just a Painted Stage Curtain
We treat the caller identity readout on modern smartphones like a wax-sealed letter delivered by a trusted courier. You assume that if the screen reads the name of your hometown depository, some sophisticated telecommunication handshake verified the signal before routing it to your antenna. In reality, the traditional phone grid treats caller identity like a blank return address line on a paper envelope—anyone holding the pen can write whatever name and number they please.
Legacy telephone architecture was built decades before digital spoofing existed, relying on an honor system where originating switches simply announced who was calling. Scammers exploit this antiquated plumbing through automated robodialers that inject counterfeit Session Initiation Protocol headers into local switches. The glowing name on your OLED panel is not an authenticated credential; it is a hollow digital mask designed to short-circuit your critical thinking through immediate panic.
When an unexpected voice claims your assets are in jeopardy, your rational brain retreats while your nervous system takes the wheel. Swindlers understand that high-friction security barriers—like two-factor authentication tokens and account passwords—fall apart when a consumer believes they are working alongside an ally to prevent catastrophe. The attack succeeds not because you are careless, but because it disguises a robbery as a rescue mission.
- Spotify offline caches hoard fifty gigabytes of phantom storage behind forgotten song downloads
- Baseus GaN chargers slash expensive replacement costs while matching blistering laptop charging speeds
- Android notification listeners intercept sensitive banking verification codes behind rogue flashlight app permissions
- Chrome Privacy Sandbox settings expose browsing habits to advertising trackers until manual toggles switch
- Thick silicone cases trap blistering charger heat degrading smartphone battery bars within months
The Cleveland Kitchen Interruption
Marcus Vance, a forty-four-year-old municipal water engineer in Cleveland, Ohio, knows how to evaluate pressure systems and faulty valves for a living. Yet on a wet Tuesday evening while packing school lunches for his daughters, his phone flashed the identical telephone number of his local credit union branch—a number saved right in his contacts. The caller knew his full legal name, his home address, and the last four digits of his debit card, warning him that someone was attempting to drain his savings from an IP address in Dallas.
The caller urged Marcus to repeat a temporary passcode sent to his mobile device to block the withdrawal. With dinner simmering on the stove and his children asking for help with their homework, Marcus nearly read off the six digits blinking in his notifications tray. A single, odd pause in the caller’s cadence gave him pause—a quiet static click that sounded less like a branch office and more like a headset breathing through an empty room. He broke the connection, walked to his hallway table, pulled out his worn wallet, and tapped the customer service number embossed directly on the plastic card. The real fraud department answered after three rings: his account was completely untouched, and the text message code he almost spoke aloud was the master reset token to wipe his online credentials.
Matching Your Defense to Your Daily Routine
Fraud robocalls do not strike everyone under the same circumstances; they catch you when your cognitive bandwidth is stretched thin. Adapting your defense requires recognizing how your daily environment shapes your vulnerability.
For the Multitasking Commuter
If you take calls through hands-free car audio while navigating rush-hour traffic, urgency works exponentially against you. You cannot inspect visual alerts or cross-reference bank balances while merging onto an interstate highway. Establish a non-negotiable rule: never authenticate account actions while behind the wheel. Treat any mid-drive call claiming urgent account fraud as an automatic hang-up; legitimate banking institutions maintain automated freeze holds that remain secure until you are parked and safe.
For the Remote Freelancer and Entrepreneur
When running a solo business or managing vendor payments, unexpected vendor calls are part of your everyday reality. Attackers exploit this rhythm by masking their voice as corporate treasury officers tracking bounced wires or payroll discrepancies. Never confirm business tax IDs or online banking verification pushes during an incoming call, regardless of whether the caller matches your commercial relationship manager’s direct office line.
For the Vigilant Household Organizer
Managing family medical expenses, school registrations, and monthly utilities requires juggle-heavy focus that makes incoming local numbers seem relevant. If a caller claims a dependent’s account is suspended or a joint mortgage payment failed, step back from the emotional hook. Household finances are resilient enough to handle a deliberate, two-minute verification delay.
The Zero-Trust Severance Protocol
Defeating high-tech telephone spoofing does not require specialized software, expensive subscription blockers, or technical expertise. It hinges entirely on taking control of the physical connection before fear dictates your choices. You must replace the instinct to answer questions with a systematic counter-habit.
Whenever a caller—human or automated—announces an immediate problem with your balance, debit card, or online profile, execute this immediate three-step reset:
- Sever the line instantly: Do not announce your intention, do not ask for a badge number, and do not say goodbye. Engaging in conversation gives trained social engineers opportunities to adjust their script to your hesitation. Hanging up immediately halts their psychological momentum.
- Breathe and retrieve your wallet: Allow the sudden rush of adrenaline to clear from your chest. Walk over to your purse, drawer, or wallet and take out the actual plastic debit or credit card tied to that institution.
- Dial the molded plastic digits: Look at the reverse side of your card. Locate the small, matte-printed 800-number resting directly above the signature strip. Dial those digits directly on your keypad.
By originating the outbound call yourself, you completely circumvent the fraudulent VoIP loop. If your bank actually flagged suspicious activity, the genuine fraud prevention representative who answers your outbound call will see the exact case notes logged in your profile. If they have no record of an issue, you have just sidestepped an aggressive credential theft without sacrificing a single penny.
• The Golden Number: The only verified customer service line is the one printed on your physical card or the back of your monthly paper statement.
• The SMS Quarantine Rule: Never dictate, forward, or confirm any code labeled ‘Do Not Share’ or ‘One-Time Passcode’ to any human voice claiming to represent that service.
• The Five-Minute Pause: Legitimate bank fraud freezes are designed to protect your balance indefinitely until verified. You have all the time you need to hang up and verify.
Reclaiming the Rhythm of Your Digital Life
There is a quiet, powerful freedom in realizing you owe nothing to a ringing smartphone. Modern telecommunications have trained us to react like lab mice to chirps, chimes, and authoritative display tags, treating every incoming notification as a command that requires an instant response. But an incoming call is simply an unverified invitation to speak, nothing more.
When you adopt the habit of hanging up and reaching for your physical card, you dismantle the psychological machinery that cyber-criminals rely on. You strip away their urgency, their rehearsed drama, and their spoofed local legitimacy. In doing so, you reclaim the calm of your living space, knowing that your financial safety is secured not by trusting what flashes on a screen, but by taking control of the line yourself.
The most secure boundary in modern consumer banking is the thin edge of your plastic debit card, where the real phone number never changes.
| Key Point | Detail | Added Value for the Reader |
|---|---|---|
| Caller ID Fallibility | VoIP systems let anyone present any outbound digits or branch names. | Eliminates false trust in caller names and local area codes. |
| Outbound Verification | Disconnect immediately and call the number printed on your payment card. | Guarantees direct connection to authorized bank servers and staff. |
| OTP Token Integrity | One-time passwords are meant solely for self-initiated account access. | Stops account takeover at the critical credential-harvesting stage. |
Frequently Asked Questions
Can my bank really not tell that someone is spoofing their phone number?
No. Because caller ID transmission relies on decentralized telecommunication routing protocols, carriers cannot consistently detect when an incoming packet has been modified to display an authorized branch number before it hits your antenna.What if the caller leaves a voicemail warning my account will be locked in 30 minutes?
Ignore the artificial deadline. Scammers use impending timelines to force rash decisions. Legitimate bank security algorithms place holds on suspected accounts until you review them, meaning your funds remain safe while you manually verify.Why did the caller already know my street address and partial card number?
Data brokers and historical third-party corporate data breaches routinely circulate credential packages online. Criminals purchase these low-cost lists and read back your own basic details to build immediate, false rapport.Will hanging up on an authentic fraud agent hurt my credit or cause extra fees?
Not at all. Actual fraud prevention personnel expect cautious customers and frequently advise consumers to terminate inbound calls and dial the official number on their card to maintain security compliance.Does enabling mobile spam-blocking apps protect me from spoofed branch calls?
Only partially. Spam filters flag numbers that have accumulated numerous community reports. Because spoofers rotate through genuine, clean bank numbers, spam software often lets these calls pass straight through as legitimate.