Amazon shares climbed more than 3% in early trading on Monday, October 19, 2026, after Morgan Stanley designated the tech giant a “Top Pick” and raised its price target to $350 from $335. In a research note issued Sunday, Morgan Stanley analyst Brian Nowak maintained an Overweight rating on the stock, outlining five core catalysts spanning cloud computing, artificial intelligence software, retail automation, and agentic commerce that the firm expects to drive material outperformance through 2028.
The updated $350 price target represents roughly 40% implied upside from Friday’s closing price of $250, according to Yahoo Finance and CNBC. With a bear-case valuation of $220 per share and a bull-case projection of $410, Morgan Stanley assesses a three-to-one risk-reward ratio for the stock ahead of Amazon’s third-quarter earnings report scheduled for October 29 after the market close.
Accelerated AWS Growth and GPU Deployment
The primary engine behind Morgan Stanley’s revised outlook is an upward adjustment to revenue and profit expectations for Amazon Web Services (AWS). Nowak raised the firm’s AWS revenue growth forecast to 47% year over year in 2027 and 42% in 2028, up from prior estimates of 41% and 37%, respectively. Over the longer term, Morgan Stanley characterizes AWS’s revenue opportunity as potentially reaching $1 trillion.
This projected acceleration is directly tied to hardware procurement. According to Yahoo Finance, the updated cloud forecast follows Nvidia’s disclosure that it expects AWS to purchase and deploy approximately 2 million of its GPUs across 2027 and 2028. To accommodate the extra silicon and associated data center expansion, Morgan Stanley increased its capital expenditure forecast for Amazon to $355 billion in 2027 and $365 billion in 2028.
Alongside top-line expansion, the firm projects expanding cloud profitability as a second major catalyst. Nowak forecasts AWS operating margins to reach 42% in 2027 and 44% in 2028. Those margin levels support Morgan Stanley’s estimate of approximately $16.50 in total Amazon earnings per share in 2028, with the $350 price target based on a multiple of roughly 21 times that 2028 earnings figure.
A third catalyst centers on Bedrock, Amazon’s managed AI model service. As enterprise artificial intelligence workloads transition from model training toward inference, Morgan Stanley argues that greater transparency and financial visibility into Bedrock’s adoption could boost Amazon’s stock valuation from its current level of roughly 15 times projected 2028 earnings.
- UK Financial Conduct Authority Plans Shift Toward Agentic AI Supervision
- Hacker Used AI Agents and $5,000 in Tokens to Breach Over 100 Company Sites
- Neocloud Shakeout Warnings and $50B Debt Strain Test US AI Buildout and Nvidia
- Elon Musk Pledges One SpaceX Share to Every Child in the U.S. Next Year
- NASA’s Perseverance Rover Sets 28.10-Mile Off-World Driving Record on Mars
Agentic Commerce and Fulfillment Robotics
Beyond cloud infrastructure, Morgan Stanley’s thesis highlights two operational catalysts within Amazon’s core retail and logistics network: AI-driven shopping agents and warehouse robotics.
While parts of Wall Street have questioned whether third-party AI assistants could disintermediate traditional e-commerce platforms, Nowak expects Amazon to emerge as a net beneficiary as AI shopping agents proliferate. According to Investor’s Business Daily, Amazon shares slid more than 4.5% the prior week amid broader market jitters and investor concerns surrounding Meta’s Muse AI agent. However, Morgan Stanley anticipates Amazon will partner over time with Meta’s Muse AI agent, leveraging its fulfillment infrastructure and customer base as the upcoming holiday shopping season serves as the first major test for agentic commerce.
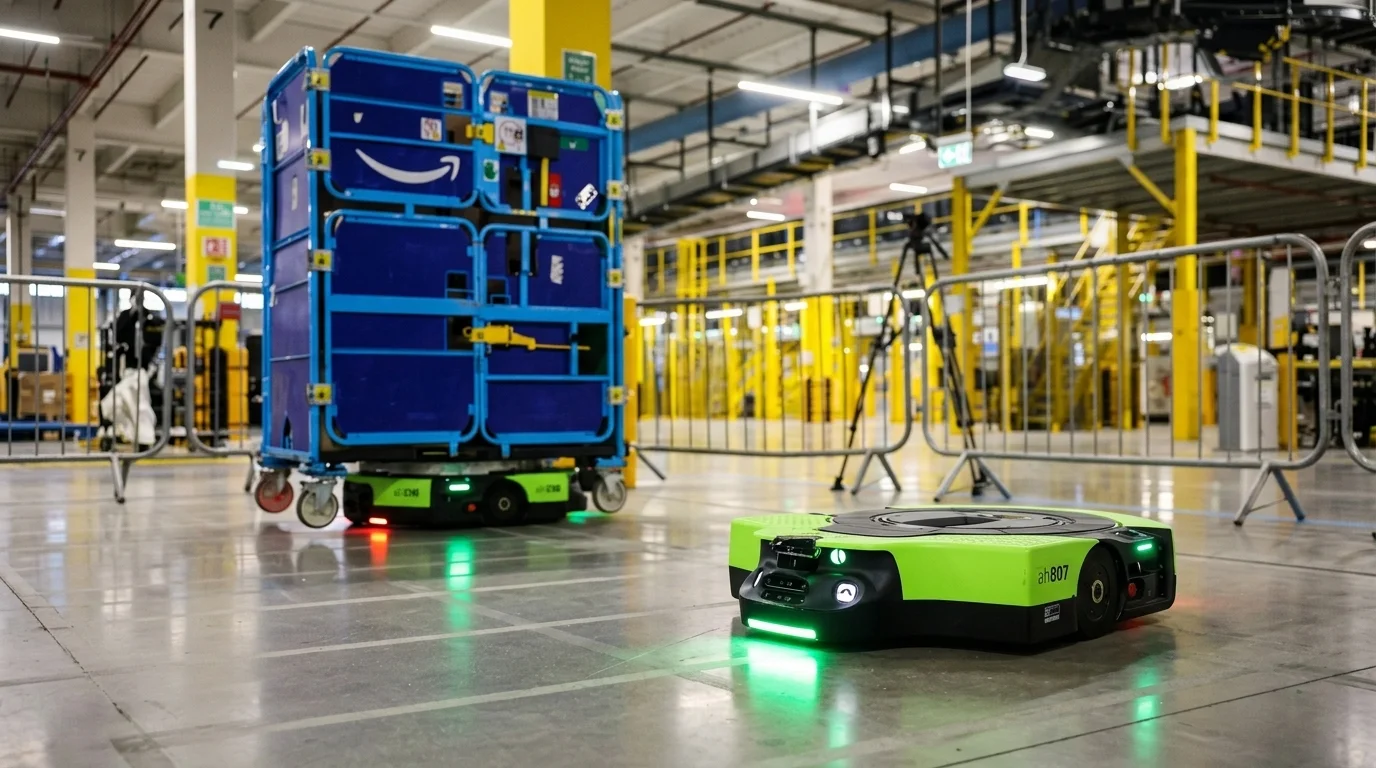
On the physical operations side, Morgan Stanley identifies fulfillment center automation as a major 2027 catalyst. Through both new facility construction and retrofits of existing warehouses, expanding robotics deployment is projected to yield substantial operating leverage. Nowak estimates that every 10% of Amazon’s global retail units routed through robotics-enabled fulfillment centers could generate between $2 billion and $4 billion in annual cost savings.
The Capital Intensity Debate and Infrastructure Bottlenecks
While Morgan Stanley’s analysis focuses on the multi-year revenue and margin payoff of Amazon’s infrastructure investments, other market reports highlight the operational friction and immense upfront cash requirements of the AI buildout. Whereas CNBC and Morgan Stanley emphasize the long-term upside of AWS expansion and Bedrock monetization, a report from Business Insider underscores the execution challenges behind Amazon’s planned $220 billion in AI infrastructure spending in 2026.
According to internal company documents reviewed by Business Insider, Amazon initiated a new “Early Rack Receipt” process in August to handle a wave of incoming server racks equipped with Nvidia’s GB300 chips at U.S. facilities. One internal email projected Amazon would take delivery of roughly $5 billion worth of Nvidia GB300 racks in August, followed by approximately $3 billion per month for the foreseeable future.
Historically, Amazon conserved cash by waiting to take financial ownership of server racks until they were installed inside a data center, leaving suppliers to carry the inventory cost in transit. Under the Early Rack Receipt procedure, intense competition for AI components has pushed Amazon to take ownership earlier in the supply chain. Because some AWS data center sites had physical floor space for racks but lacked sufficient electrical power to turn them on, equipment has had to be staged at intermediary warehouses, compressing cash flow timelines before the hardware can begin generating cloud revenue.
Dan Ives, an analyst at Yorkville Ives, noted in a recent report cited by Business Insider that the broader equity market is repricing companies that fund multi-year infrastructure builds against revenue that arrives later, particularly amid permitting delays and political debates over electricity prices.
Market Context and What It Means for Investors
Despite near-term debates over capital intensity, Amazon’s recent financial performance has demonstrated accelerating cloud demand. As reported by TradingView, Amazon’s second-quarter revenue rose 19.6% year over year to $200.6 billion, while AWS revenue grew 37%—its fastest pace in 18 quarters, beating consensus expectations of 31% growth and lifting the cloud unit’s backlog to $496 billion. Second-quarter GAAP earnings per share reached $5.75, boosted by $53.4 billion in one-time, non-operating income tied to Amazon’s investment in AI developer Anthropic.
CEO Andy Jassy has maintained that the company has a clear line of sight to strong financial returns from its capital expenditure cycle, describing AI in his annual shareholder letter as a “once in a lifetime opportunity” that mirrors the initial AWS buildout wave.
In trading on Monday, TradingView noted Amazon shares rose 3.3% to $260.07 amid a broader technology rebound that saw the Nasdaq advance more than 1% in pre-market action. Depending on the intraday baseline used, Yahoo Finance reported the stock is up roughly 11% year to date and sits about 10% below its early August high, while TradingView calculated a 14.8% year-to-date gain relative to its August 2026 52-week high of $284.02.
Frequently Asked Questions
What is driving Morgan Stanley’s forecast for faster AWS revenue growth?
Morgan Stanley raised its AWS revenue growth projections to 47% in 2027 and 42% in 2028 following Nvidia’s disclosure that AWS is expected to purchase and deploy roughly 2 million Nvidia GPUs over that two-year span, alongside broadening enterprise adoption of the Bedrock AI platform.
How will AI shopping agents affect Amazon’s retail business?
While some investors worry third-party AI assistants could bypass traditional retail sites, Morgan Stanley expects Amazon’s logistics scale and customer base to make it a primary beneficiary of agentic commerce, projecting a future partnership with Meta’s Muse AI agent and pointing to the upcoming holiday season as an initial test.
How much could warehouse robotics save Amazon?
Morgan Stanley estimates that every 10% of Amazon’s global units moving through robotics-enabled fulfillment centers could save the company between $2 billion and $4 billion annually, positioning physical warehouse automation as a key profit driver starting in 2027.
Sources
- Yahoo Finance – Amazon stock pops after Morgan Stanley details 5 catalysts, lifts price target
- Business Insider – Amazon knows how to build big. The AI boom is testing just how big it can go.
- TradingView – Why Amazon (AMZN) Stock Is Up Today
- CNBC – Amazon is a top pick and will get a big boost from a slew of catalysts, says Morgan Stanley
- Investor’s Business Daily – Why Amazon Stock Is A ‘Top Pick’ Despite Investor Fears About Meta’s Muse