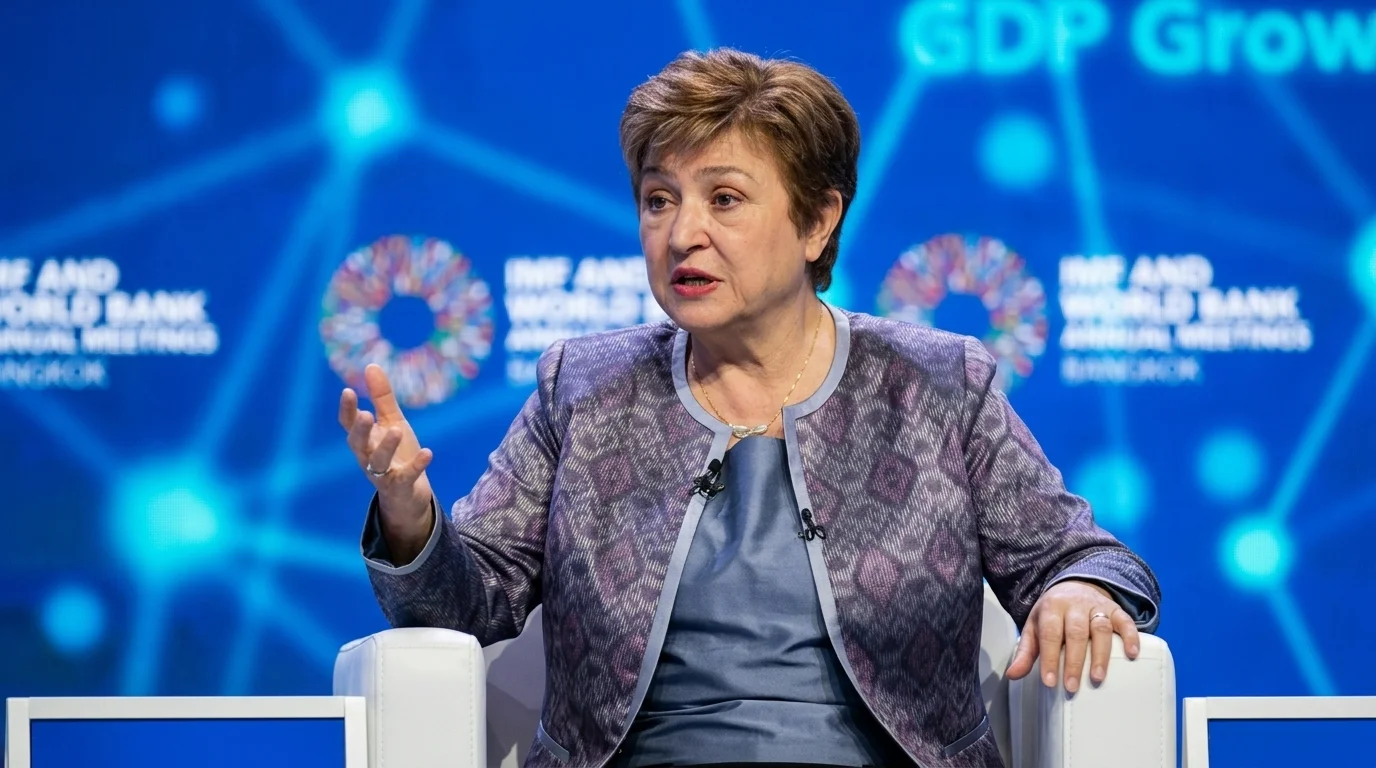
Global economic leaders gathered in Bangkok for the International Monetary Fund (IMF) and World Bank annual meetings this week warned that while artificial intelligence infrastructure spending is currently propping up international growth, any sudden drop in confidence could trigger severe financial shocks. According to Agence France-Presse, surging capital expenditures on data centers and microchips have helped keep global economic growth above 3% in 2026, offsetting the economic drag of rising energy prices linked to conflict in the Middle East. However, central bankers and economists caution that heavy reliance on the sector leaves global markets exposed if expected productivity gains fail to materialize or if regulatory disputes stall adoption.
The Economic Cushion and the Threat of a Pullback
Data presented during the Bangkok summit illustrates the scale of the technology sector’s recent footprint on physical trade and domestic output. IMF Chief Economist Silvana Tenreyro noted that global trade expanded by 8.3% between 2023 and 2025, adding that the figure would have been closer to 4.6% without trade in AI-related hardware and products, as reported by Daily Sabah. Bank of Canada Governor Tiff Macklem told attendees on Friday that the technology’s influence is now visible across gross domestic product (GDP) metrics, equity markets, and bond yields.
Despite the strong top-line numbers, financial officials expressed concern over market concentration and uncertain long-term business models. Federal Reserve Chair Kevin Warsh described artificial intelligence as the most consequential economic shift of his lifetime, but cautioned that the transition would be bumpy due to uncertainty over how the market structure for these technologies will settle.
According to Reuters, an IMF scenario analysis released this week found that if anticipated AI productivity gains fall short and capital investment drops sharply, United States GDP could take a direct hit of 0.8%. Spillover effects hitting Asian hardware exporters and supply chains could reduce total global GDP by 0.4% by 2028. IMF Managing Director Kristalina Georgieva warned that a sudden loss of investor confidence could prompt capital flight from the sector, creating broader financial stability risks.
Macroeconomic pressures outside the technology industry could also test the durability of the spending boom. In an October 14 briefing, the IMF framed the global outlook as a contest between two opposing forces: a positive demand shock driven by AI investment and a negative energy-supply shock stemming from the Middle East conflict. Economists at Moody’s Analytics warned that a prolonged conflict could drive up energy costs and interest rates, straining the operating economics of power-hungry data centers and puncturing the investment boom.
- China Unveils First 100,000-Card Domestic AI Supercluster Hardware in Shenzhen
- Connecticut Officials Seek Regulatory Probe Into Utility AI Risks
- Trump Accounts Sell Micron Shares and Buy Up to $25.3 Million in Meta Stock
- Waymo Plans First Canadian Robotaxi Service in Toronto by 2028
- U.S. Retailers Face Backlash Over AI Pricing Tools as States Enact New Rules
Labor Disruption and Uneven Global Gains
Beyond balance-sheet vulnerabilities, policymakers are confronting structural changes in global labor markets and tax bases. According to Reuters, Georgieva cited IMF research indicating that roughly 40% of jobs worldwide—and up to 60% of roles in advanced economies—could be augmented, downgraded, or eliminated by artificial intelligence. This shift carries direct consequences for public finance, as automation threatens to shift national tax revenues away from labor income and toward capital.
The economic upside of the technology boom is also concentrated geographically. The IMF noted that a narrow group of nations accounts for an increasing share of global output, with primary gains flowing to jurisdictions that manufacture semiconductor hardware or host major software platforms, leaving developing economies at risk of falling further behind.
The debate over how machines affect human labor also extends into education and workforce evaluation. As tech executives and political figures increasingly frame AI capabilities around human metrics like intelligence quotients (IQ), historians warn against relying on flawed benchmarks. An analysis in The Conversation noted that universities and policymakers evaluating what tasks AI might replace must recognize the troubled history of IQ testing, which was used in the early 20th century to justify exclusionary educational policies.
A Widening Divide Over AI Governance
As the economic stakes rise, international consensus on how to regulate advanced models remains fractured. In Bangkok, Georgieva linked market durability directly to oversight, stating on Friday that without proper safeguards, the risks of the technology could outweigh its economic opportunities.
However, the United States has largely pivoted away from binding federal mandates in favor of rapid commercial deployment and industry self-policing. According to the Los Angeles Times, President Donald Trump’s administration has rolled back prior requirements that forced developers to share safety test results with federal agencies and issued a December executive order aimed at blocking state-level AI rules. In late September, a White House meeting yielded a nonbinding, 308-word voluntary safety accord asking companies to maintain internal monitoring teams, though the administration has not specified how those internal controls will prevent harmful outcomes.
This domestic approach contrasts with urgent appeals from some industry executives and international bodies. According to a policy briefing by Faegre Drinker, while U.S. officials at the United Nations rejected proposals for new international AI governance bodies in late September, several AI executives and technical experts briefed the UN Security Council to call for coordinated risk-evaluation standards and mandatory safety disclosures.
Even without sweeping new legislation, U.S. agencies are using existing liability and consumer protection frameworks to police the sector. As reported by Insurance Journal, a newly launched federal AI task force warned software developers in early October to report and fix security vulnerabilities or face legal consequences, while the Federal Trade Commission has stepped up scrutiny of AI companies following recent cybersecurity incidents.
Key Questions Facing Policymakers and the Public
How will U.S. policymakers address worker displacement and potential erosion of payroll-tax revenues as AI changes jobs?
With IMF research projecting that up to 60% of jobs in advanced economies could be altered or eliminated by AI, governments face a potential shift of income from labor to capital. While international economists have flagged the need for education reform and tax policy adjustments, concrete legislative measures in the U.S. remain secondary to debates over infrastructure growth and deregulation.
If federal policy favors voluntary company safeguards, what mechanisms verify compliance?
Under the late-September White House safety accord, monitoring relies on internal company controls rather than independent pre-deployment testing. Rather than establishing a dedicated federal regulator, the administration is currently relying on post-incident enforcement through existing bodies like the Federal Trade Commission and a federal AI task force focused on cybersecurity liability.
What protections could reduce the risk that an AI investment bust harms financial stability?
Central bankers and the IMF have emphasized monitoring capital markets for overvaluation and ensuring that rising energy costs and interest rates do not trigger a sudden credit crunch among heavily leveraged technology providers and data center operators.
Sources
- Agence France-Presse – Leaders weigh ‘huge benefit’, risks of AI for global economy
- Daily Sabah – World leaders weigh on AI’s role as driver of growth, its risks
- Reuters – AI investment props up global growth, but war and debt threaten outlook, IMF says
- Reuters – IMF says AI investment keeps global growth around 3% but brings massive disruption
- International Monetary Fund – Press Briefing Transcript: Global Policy Agenda, Annual Meetings 2026
- The Conversation – Why the ugly history of IQ testing matters for AI and education
- Los Angeles Times – In Silicon Valley, AI founders cheer Trump’s calls for industry to police itself on safety
- Faegre Drinker – Global and Domestic Policymakers Struggle to Keep Pace With AI Advancement
- Insurance Journal – AI Liability and Federal Scrutiny