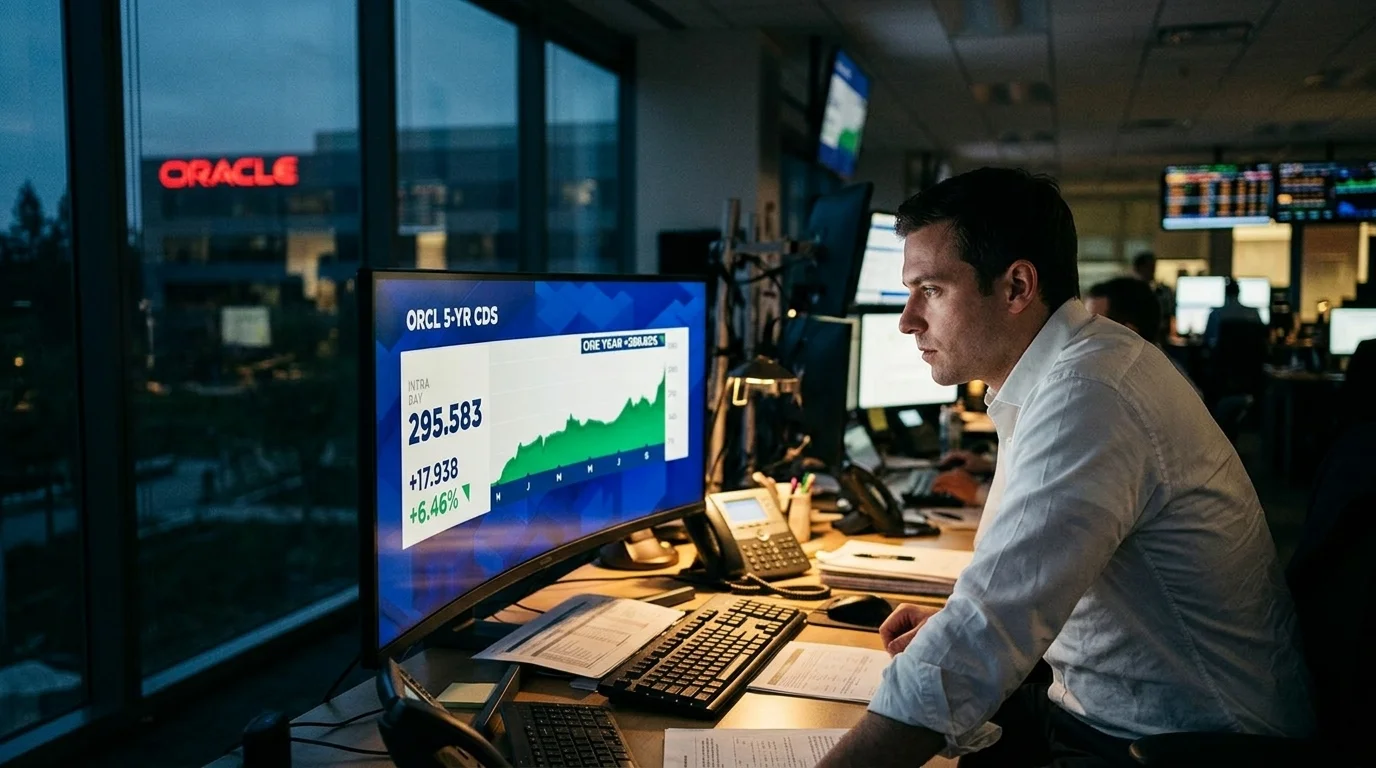
Fixed-income investors are repricing the risk of debt-funded artificial intelligence infrastructure, turning Oracle Corporation into a primary bellwether for the tech sector’s capital expenditure boom. In mid-October 2026, the cost of insuring Oracle’s debt against default surged to multi-year highs, driven by concerns over how quickly massive data center investments will generate positive cash flow amid elevated interest rates.
While equity markets have largely celebrated the multi-year AI buildout, bond and derivatives traders are zeroing in on the balance sheets financing the physical expansion. According to CNBC, the spread on Oracle’s five-year credit default swaps (CDS)—contracts that act as insurance against a company defaulting on its debt—recently climbed to 295 basis points after briefly touching 300 basis points, marking a 287% increase over the past year. Reuters noted that the spread widened by 26 basis points overnight on October 15 to hit 288 basis points, reflecting heightened nervousness across both equity and fixed-income markets.
The core issue unsettling credit markets is a timing mismatch: enterprise cloud providers must borrow tens of billions of dollars today to construct data centers and purchase AI chips, while the resulting revenue streams will take years to materialize.
Why Oracle Is the AI Credit Bellwether
Historically known for enterprise database software, Oracle has aggressively pivoted into cloud infrastructure to compete with larger hyperscalers, highlighted by a massive $300 billion deal with OpenAI. To finance this rapid footprint expansion, Oracle has accumulated $118 billion in long-term debt alongside $39 billion in capital and lease obligations, according to FactSet data cited by CNBC.
That heavy borrowing places Oracle at the weaker end of the investment-grade credit spectrum. In July 2026, S&P Global Ratings downgraded Oracle to BBB-, which sits just one notch above speculative-grade, or “junk,” status. Despite maintaining an investment-grade rating, Oracle’s recent CDS spreads have traded in ranges more typical of high-yield BB and B rated debt, Gavan Nolan, executive director of fixed income pricing at S&P Global Market Intelligence, told CNBC.
- Georgetown Report Details How Government Agencies Can Optimize Websites for AI Crawlers
- Jerusalem Post Analysis Examines How AI Tools Expose Israel’s Political Circles
- GAO Releases 2027-2032 Strategic Plan to Audit Federal AI and Hire Tech Specialists
- NYC Public Schools Halts Generative AI Use Through 8th Grade for 2026-27 Year
- AI Skills Carry Nearly $18,000 Wage Premium as Data Questions 120,000 AI Job Cuts
Because Oracle’s credit derivatives are highly liquid and its debt load is substantial relative to its current cash generation, traders use the company as a visible proxy for the broader AI infrastructure trade. As Reuters points out, a widening CDS spread is a market indicator of perceived risk rather than an imminent forecast of default. However, the repricing has spilled over into equities. According to Reuters, Oracle shares dropped 7.2% on October 14 alongside declines in its dollar bonds, followed by another 2% slide on October 15 during a broader tech selloff that erased roughly $80 billion in market value across AI-linked firms.
The Cash Flow Gap and Off-Balance-Sheet Commitments
The tension between top-line AI growth and upfront capital demands is stark in Oracle’s financial metrics. According to a financial summary from TokenPost covering Oracle’s fiscal first quarter ended August 31, 2026, the company’s cloud infrastructure revenue rose 121% year over year to $7.4 billion. However, capital expenditure for the three-month period reached roughly $28.5 billion, outstripping operating cash flow of $23.1 billion and resulting in non-GAAP free cash flow of negative $5.4 billion.
Looking ahead, consensus analyst forecasts cited by CNBC project Oracle’s free cash flow will remain deeply negative as construction continues, estimating outflows of -$23.7 billion this year and -$36 billion in 2027.
Investors are also scrutinizing long-term obligations that do not yet appear as funded debt. As of August 31, Oracle reported $664 billion in companywide remaining performance obligations (RPO)—a measure of contracted backlog—though only about 13% is expected to convert into recognized revenue over the next 12 months, TokenPost reported. At the same time, the company disclosed $288 billion in additional lease commitments, substantially all tied to data centers, expected to commence between the second quarter of fiscal 2027 and fiscal 2029 with terms running 15 to 19 years.
The scale of physical financing is also testing banking syndicates. According to Yahoo Finance, summarizing reporting from Bloomberg, banks arranged roughly $38 billion in construction financing for two Vantage Data Centers campuses linked to Oracle, a package that took months to distribute across lenders and investors.
A $7 Trillion Industry Buildout vs. Downgrade Risks
Oracle’s spending is part of an unprecedented capital cycle across the technology sector. In an analysis reported by Investing.com via Reuters, S&P Global estimated that the six largest US hyperscalers—Amazon, Microsoft, Alphabet, Oracle, Meta, and SpaceX—could spend more than $7 trillion combined on data centers and AI-related capital expenditures between 2025 and 2030.
While S&P expects negative free cash flow across the cohort to persist at least through next year, the rating agency noted it sees no immediate need for rating changes among the top tier. Still, S&P outlined specific triggers in July that could push Oracle into junk territory: sustaining leverage above 4x, failing to establish a clear trajectory toward positive free operating cash flow by fiscal 2029, or a broader deterioration in the outlook for Oracle’s AI strategy.
What this means for the market comes down to the mechanics of institutional bond portfolios. Jim Reid, global head of macro and thematic research at Deutsche Bank, warned in a report cited by CNBC that a downgrade of Oracle into junk territory would risk forcing investment-grade-only institutional investors to sell their holdings.
Losing investment-grade status would also alter how Oracle funds its operations. Jamie Meyers, a senior securities analyst at Laffer Tengler, which holds Oracle stock, told CNBC that high-yield investors do not buy 30-year debt, meaning a downgrade would force Oracle to issue shorter-duration debt at higher interest rates. However, both Meyers and Vanguard fixed-income portfolio manager Brad Collins expressed confidence to CNBC that Oracle will defend its investment-grade rating, arguing the company simply needs time to finish building its facilities so contracted revenue can begin ramping.
Frequently Asked Questions
Why are Oracle’s credit default swaps rising if the company is growing?
Credit default swaps measure the cost of insuring bondholders against a default. Even though Oracle’s cloud revenue is growing rapidly, the company is borrowing tens of billions of dollars upfront to build data centers, resulting in negative free cash flow. Fixed-income traders are pricing in the risk of carrying that heavy debt load before the new facilities generate consistent cash returns.
Does Oracle’s $664 billion backlog guarantee near-term debt repayment?
Not immediately. While $664 billion in remaining performance obligations shows strong multi-year customer demand across all of Oracle’s business lines, only about 13% is projected to convert into actual revenue over the next 12 months. Converting the rest requires bringing data centers online over several years.
What happens if S&P downgrades Oracle from BBB- to junk status?
A downgrade below BBB- would move Oracle into speculative-grade (high-yield) territory. This could trigger forced selling by institutional funds mandated to hold only investment-grade bonds, raise Oracle’s borrowing costs, and restrict its ability to issue long-term, 30-year bonds to fund long-lived data center assets.
Sources
- CNBC – Credit stress is threatening to unwind the AI bull. All eyes are on Oracle to hold the line
- Reuters – AI credit worries send default insurance to record high
- Reuters – Why are credit default swaps unnerving AI investors?
- Reuters – AI infrastructure firms slump as US rate hike bets rise
- Reuters – Nasdaq futures dive as AI rout deepens on debt concerns
- Investing.com / Reuters – Top hyperscalers likely to have more AI-linked debt than now known, S&P Global warns
- TokenPost – Oracle Q1 Fiscal Results and Infrastructure Commitments Summary
- Yahoo Finance – Banks Arranged $38 Billion in AI Data Center Loans