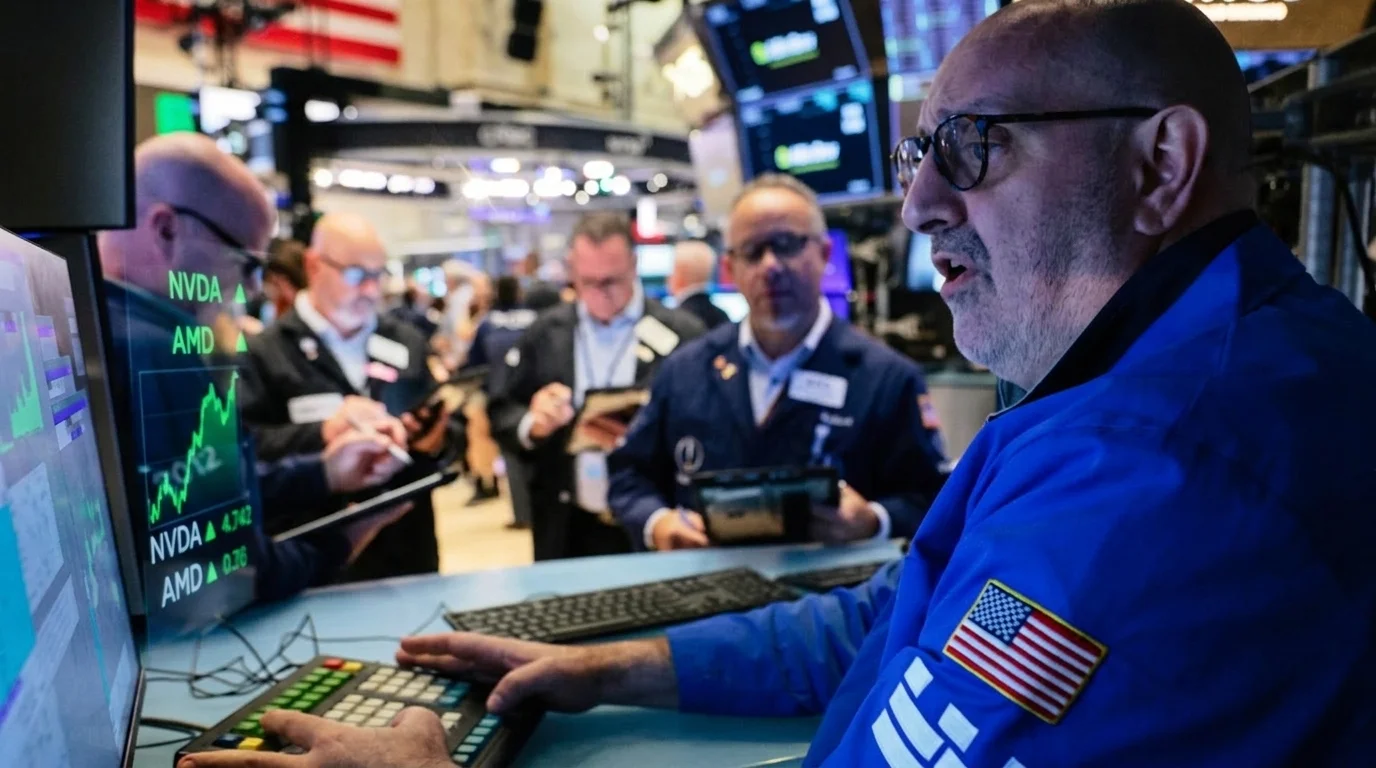
U.S. technology and semiconductor stocks staged a targeted recovery on Monday, October 19, 2026, led by artificial intelligence chipmakers Advanced Micro Devices (AMD) and Nvidia. The bounce followed the steepest weekly market declines since late June and arrives just ahead of third-quarter earnings reports from Netflix, SpaceX, Meta Platforms, and Tesla. Easing Treasury yields and falling oil prices helped stabilize sentiment after a multi-day selloff driven by anxiety over the rising cost of financing AI data center infrastructure.
According to market closing data from Reuters, the S&P 500 rose 34.27 points, or 0.45%, to finish at 7,693.71, while the Nasdaq Composite gained 249.13 points, or 0.95%, to close at 26,389.16. Despite the headline index gains, most individual S&P 500 constituents declined during the session, with the technology sector’s 1.2% advance doing the heavy lifting. Meanwhile, Investor’s Business Daily noted that the Dow Jones Industrial Average slipped 36 points, and Yahoo Finance characterized the broader session as mixed, tracking the Dow down 0.2%, the S&P 500 up 0.5%, and the Nasdaq up roughly 1%.
Semiconductors Snap Multi-Day Losing Streak
Hardware providers bore the brunt of the prior week’s pullback, making Monday’s reversal a key focal point for portfolio managers. Over the five-day span ending Friday, October 16, the S&P 500 fell nearly 2% and the Nasdaq Composite dropped 4.5%, according to CNBC. Chipmakers endured an even sharper contraction. Reuters noted that semiconductor stocks had suffered eight consecutive losing sessions, while Investor’s Business Daily reported that the Philadelphia Semiconductor Index plunged 15.7% over that eight-day stretch, marking its longest losing streak in eight years.
On Monday, buyers stepped back into oversold hardware names. Intraday snapshots showed steady accumulation across the sector: Reuters recorded early session gains of 3.6% for AMD, 1.5% for Nvidia, and 2.4% for Broadcom, while Investor’s Business Daily tracked morning trade moves of more than 3% for AMD, 1.7% for Nvidia, and a 2.7% rebound for the Philadelphia Semiconductor Index. By the closing bell, Broadcom held a 2.2% gain and memory maker Micron climbed 4.3%.
- WBUR and News Outlets Break Down AI Jargon as Autonomous Agents Enter Mainstream Use
- AICPA and AIUC Launch Combined SOC 2 and AI Agent Assurance Certification
- NBA Expands AI Integration Across Officiating, Broadcasts, and Fan App Features
- U.S. Banks Block Third-Party AI Agents From Moving Customer Money
- Massachusetts Students Examine How AI Reshapes Work and Careers at WPI Studio
The recovery extended across the global semiconductor supply chain and adjacent compute providers:
- Intel: Shares advanced 4.5% after JPMorgan upgraded the chipmaker to Neutral from Underweight, pointing to growing agentic-AI workloads and tight supply of advanced chips as potential tailwinds for estimate revisions through 2027.
- Memory and International Suppliers: The iShares MSCI South Korea ETF (EWY), heavily weighted toward memory giants SK Hynix and Samsung Electronics, climbed 4% following steep prior-week losses, while the iShares Semiconductor ETF (SOXX) moved to snap a nine-day slump.
- Cloud Infrastructure: AI infrastructure provider CoreWeave also drew support after receiving an analyst upgrade from Goldman Sachs.
Infrastructure Financing and the ‘Earnings-Expectation Bubble’
The underlying tension in the technology sector centers on whether massive capital expenditures on AI data centers will generate proportional near-term revenue. As noted in a Reuters analysis, the previous week’s selloff was triggered by fears that elevated interest rates could restrict capital access for data-center operators funding large-scale hardware build-outs.
Wall Street strategists suggest the market is transitioning from indiscriminate AI enthusiasm to strict balance-sheet scrutiny. Ron Albahary, chief investment officer at LNW, told CNBC that investors now require concrete proof statements from companies tied to the AI trade to justify their current pricing. Rather than comparing the current environment to the dot-com valuation bubble, Albahary described the present dynamic as an “earnings-expectation-potential bubble.”
This shift is expected to create greater separation between corporate winners and losers. While established cash-generating tech giants may continue to attract capital, Albahary warned that specialized “neocloud” platforms could face selling pressure due to the heavy debt loads required to finance their server build-outs. Sameer Samana, head of global equities and real assets at the Wells Fargo Investment Institute, characterized the recent market action as a “reality check” rather than a complete unraveling, though he cautioned that selling pressure could persist through the midterm elections due to the increasing politicization of AI and data center power consumption.
High Stakes for This Week’s Tech Earnings
Whether Monday’s rebound holds depends heavily on corporate disclosures over the next several days. According to CNBC, 85% of the 47 S&P 500 companies that have reported third-quarter results so far have beaten analyst estimates, putting the index on pace for a blended earnings growth rate of 29%. Broader consensus data cited by Yahoo Finance projects S&P 500 earnings growth at 29.6% for the season—which, if realized, would mark a third consecutive quarter of growth exceeding 25%.
The reporting calendar accelerates immediately, according to schedules from Business Insider and Investopedia:
- Tuesday, October 20: Netflix and SpaceX are scheduled to report quarterly results, offering an early gauge of consumer subscription resilience and aerospace-linked enterprise demand.
- Wednesday, October 21: Meta Platforms, Tesla, and IBM report after the market closes, with Meta’s conference call scheduled for 5:30 p.m. Eastern. Analysts expect Meta to beat consensus estimates, according to a Reuters preview, though investor reaction will hinge on forward capital expenditure guidance.
- Next Week and Beyond: The test for Big Tech continues the week of October 26 with results from Alphabet, Microsoft, and Amazon, followed by Apple on November 2.
Frequently Asked Questions
Will Meta and Tesla results validate current AI capital spending?
Analysts expect Meta to beat third-quarter expectations on Wednesday, but market stability depends on forward guidance. Investors are looking for direct evidence that heavy spending on AI compute clusters is driving measurable revenue growth in core advertising, software, and autonomous systems without compressing operating margins.
Why did semiconductor stocks sell off so sharply last week?
The eight-session semiconductor slump was driven by rising Treasury yields and macroeconomic concerns that higher borrowing costs would force data center operators and neocloud providers to slow down their purchases of expensive AI server racks.
Is Monday’s rebound a broad market recovery?
Not yet. While the S&P 500 and Nasdaq finished higher on Monday, most individual stocks within the S&P 500 actually declined. The gains were heavily concentrated in large-cap technology and semiconductor names benefiting from dip-buying and a single-day pullback in oil prices and bond yields.
Sources
- CNBC – Tech stocks had a nice oversold bounce on Monday. Earnings this week will determine if it’s for real
- Reuters (via Fidelity) – S&P 500, Nasdaq climb as AI-linked stocks recover ahead of earnings
- Reuters – AI stocks bounce back after bruising selloff, CoreWeave gets Goldman upgrade
- Reuters (via Fidelity) – S&P 500 and Nasdaq futures rise as AI stocks rebound ahead of key earnings
- Investor’s Business Daily – Dow Jones Futures: AMD, Nvidia Lead AI Trade Higher; Meta, Netflix, SpaceX, Tesla Earnings On Deck
- Investor’s Business Daily – Chip Stocks Rebound, AI Names Leaders Nvidia, AMD
- Reuters – Wall St futures climb as AI stocks rebound, oil and yields fall
- Business Insider – Major Earnings This Week October 19-23, 2026
- Investopedia – What to Expect in Markets This Week
- Yahoo Finance – Earnings Live Updates: Q3 Earnings Roll On
- Yahoo Finance – Stock Market Today: Dow, S&P 500, Nasdaq Mixed Amid Volatile Week